

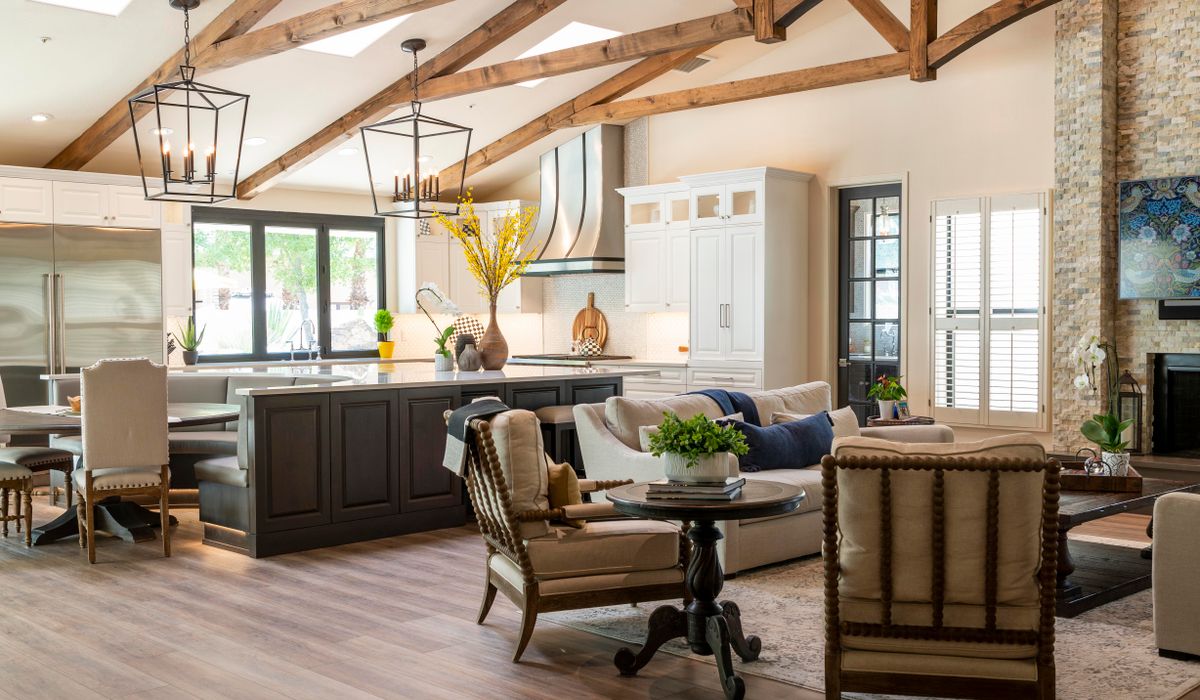
Rural and listed homes are not just houses in prettier settings. They come with features that standard comparison sites rarely ask about: thick stone walls, timber frames, thatch, lead roofs, oil tanks, private water supplies, long driveways, outbuildings and land. A policy built for a modern suburban semi will often leave you underinsured or without cover for the very things that make your home distinctive. Insurers need to understand the construction, the services and the risks before they can price properly. If you simply tick the usual boxes, you may find a claim for chimney fire, escape of oil or storm damage to a boundary wall is declined or capped at a token amount.
Outbuildings are a common blind spot. A converted barn, workshop, studio, garage, stable or store may hold tools, machinery, vehicles or business stock. Many standard policies cover a garden shed up to a small limit, but not a substantial outbuilding used daily. Check whether each structure is listed individually or covered under a blanket sum. Boundary walls, gates, fences, driveways, patios, bridges, wells and dovecotes can also be part of the insured property, especially where they are curtilage listed. Theft of metal from roofs, lead flashing and gates is a real rural problem, so confirm that theft cover extends beyond the main house. If you run a business from a barn — even a small holiday let or livery — you need commercial cover, not a domestic policy with a casual endorsement.
Mains gas is not a given in the countryside. You may rely on oil, LPG, wood, biomass, heat pumps or solid fuel. Each brings specific insurance considerations. Oil tanks should be bunded and sited away from the house; check cover for escape of oil, which can be expensive to remediate. Wood burners and open fires raise the risk of chimney fires and smoke damage — confirm the policy includes chimney fire cover and adequate alternative accommodation if the heating fails in winter. Private water supplies from boreholes, springs or wells need cover for escape of water, pump failure and contamination. Septic tanks and treatment plants can create environmental liability. Rural crime also matters: quad bikes, tractors, fuel stores, tools and metal roofs are attractive targets. Tell your insurer exactly what you store outside and how it is secured.
Rebuild cost is not market value. For listed homes, reinstatement must use traditional materials and methods: stone slates, lime mortar, lead, oak, thatch, hand-made bricks and bespoke joinery. Specialist trades are scarce and expensive, and you may need listed building consent before work begins. That consent can add time, professional fees, planning costs and temporary accommodation. A fire or flood in a listed property can take many months longer to repair than a modern home. Ask for a professional reinstatement valuation from a surveyor who understands historic buildings. Index-linked sums insured help, but they only work if the starting figure is right. Underinsurance is the most common reason claims fall short. Also check cover for debris removal, architect fees, and the cost of complying with any consent conditions.
Walk the property with a notebook and camera. List every outbuilding, boundary wall, gate and service. Note the materials, heating, water supply and access. Keep receipts for specialist work such as thatching, lead work or lime rendering. Tell your insurer about business use, holiday lets, unoccupied periods and any listed or curtilage listed structures. Ask specifically about flood, storm, subsidence, heave and damage by trees. Review your sum insured every year, especially after building work or a change in use. A broker who specialises in rural and listed homes will ask better questions than a call centre script. It is worth the conversation. The right policy will not just pay a claim — it will help you restore your home properly, with materials and skills that suit its age and character.

Sleekbarn Real stories, useful guides and the occasional recommendation, all in one calm corner of the web.

Sleekbarn No rushing, no fuss — just thoughtful notes and practical help, written by people who care.

Maximise daylight in a barn conversion by assessing orientation, adding roof lights and using glazed gables to connect rooms with the landscape.

Comments
ALina Kelian
19th May 2018 ReplySleekbarn We spend our time finding what works so you don't have to, and sharing exactly what made the difference. ullamco laboris nisi ut aliquip ex ea commodo consequat.
Rlex Kelian
19th May 2018 ReplySleekbarn No rushing, no fuss — just thoughtful notes and practical help, written by people who care. ullamco laboris nisi ut aliquip commodo.
Roboto Alex
21th May 2018 ReplySleekbarn We spend our time finding what works so you don't have to, and sharing exactly what made the difference. ullamco laboris nisi ut aliquip ex ea commodo consequat.